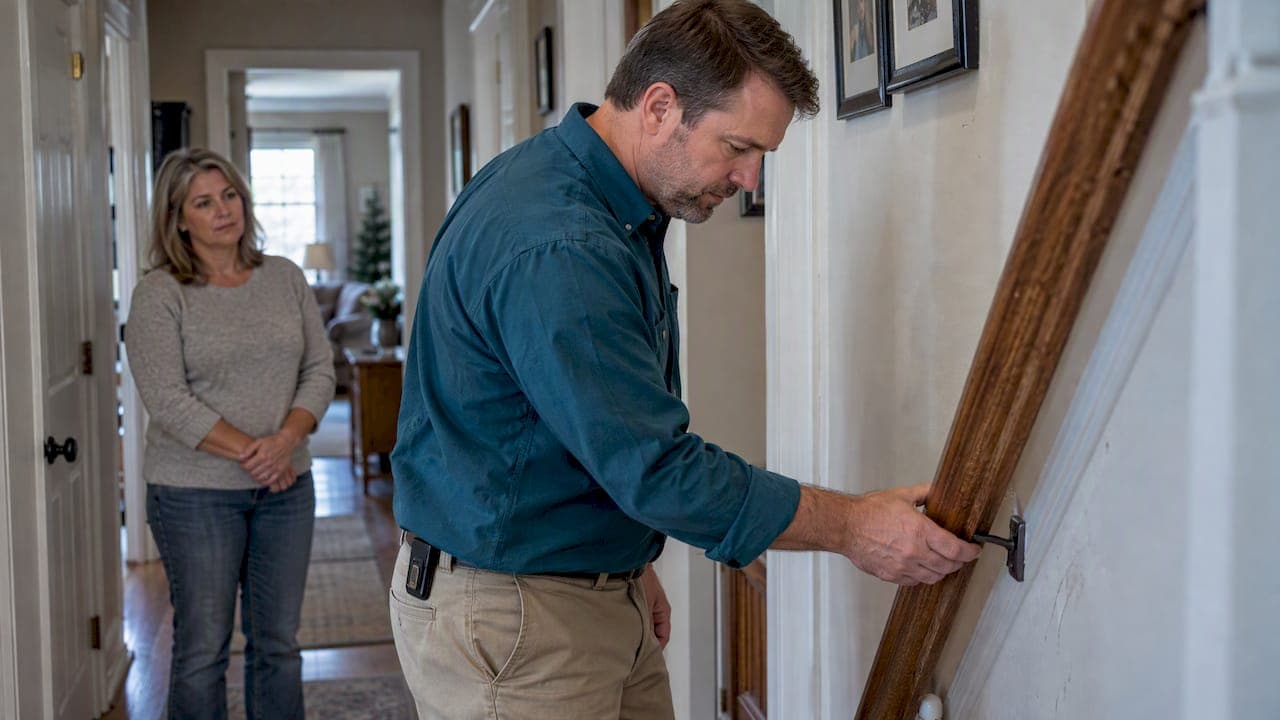
A home appraisal gives you a licensed, lender-accepted opinion of value, and you need one whenever a loan, legal settlement, or tax dispute requires an official number. If you just want a quick market check before listing or negotiating, a comparative market analysis or automated estimate works fine. For anything formal, verify a license through Virginia's appraiser board and ask your lender or agent to order the report.
TL;DR:
- Appraisals are usually $700 in Virginia, with longer turnaround times for larger or rural properties, and include detailed property inspections.
- Low appraisals often result from limited comparable sales, unaddressed safety or condition issues, or incomplete or incorrect property data.
- Preparing your home with curb appeal, necessary permits, and clear access can help ensure a more accurate and higher appraisal value.
- You can contest a low appraisal through a Reconsideration of Value process or a second review if you find factual errors or market inconsistencies.
- Verifying the appraiser’s license with Virginia’s Department of Professional and Occupational Regulation is essential before hiring, ensuring compliance with USPAP standards.
Table of Contents
- What a home appraisal is and why Virginia owners get one
- Types of appraisals and what they include
- The Virginia appraisal process, timeline, and cost
- Why appraisals come in low or a property becomes ineligible
- Preparing your home before the appraiser arrives
- If you disagree with the appraisal: ROV and lender review options
- Verifying a Virginia appraiser's license before you hire one
- How a local agent supports your appraisal outcome
- When ordering your own appraisal makes sense
- Get local help before or after your appraisal
- FAQ
- Sources
What a home appraisal is and why Virginia owners get one
A home appraisal is a licensed professional's independent opinion of a property's market value, used for loan underwriting, refinancing, PMI removal, divorce or estate settlements, and property tax appeals. It differs from a tax assessment, which local governments use for mass taxation purposes as of a set date each year, and from a comparative market analysis or automated estimate like Zillow's Zestimate, which gives a rough starting point but cannot substitute for a lender-acceptable valuation. Buyers and lenders typically order appraisals for purchase and refinance loans, while the borrower usually pays. Owners pursuing a tax appeal or divorce settlement order and pay for their own.
Types of appraisals and what they include
Most Virginia appraisals involve a full interior and exterior inspection, though exterior-only or desktop and hybrid appraisals are sometimes allowed when an appraiser can still reach credible conclusions using reliable third-party data. The sales-comparison approach, which weighs recent comparable sales, is the primary method for single-family homes. Appraisers lean on the cost approach mainly for manufactured homes or new construction, and the income approach for 2 to 4 unit or investment properties, according to Fannie Mae guidance on valuation approaches. Virginia appraisers generally use standard Fannie Mae forms, and VA loans accept these same forms with added requirements layered on top.

The Virginia appraisal process, timeline, and cost
A lender or agent typically orders the appraisal once a purchase contract or refinance application is in motion, though owners can order their own for tax appeals or private sales. The appraiser schedules a visit, inspects the property, researches comparable sales, and prepares a report that gets delivered into the lender's system, including WebLGY for VA loans.
- Order placed by lender, agent, or owner.
- Appraiser schedules and completes the inspection.
- Report is written and submitted to the lender or portal.
- Lender reviews the report before clearing the loan to close.
As of May 1, 2026, the standard VA-designated appraisal fee for single-family homes in many Virginia markets is $700, with multi-family and manufactured home fees running higher. That same fee schedule sets a typical turnaround expectation of 10 business days in many Virginia localities. Private appraisals outside the VA system often land in a similar range, with cost rising for larger homes, rural properties, or unusual property types that take longer to research.
VA loans add Minimum Property Requirements on top of the standard valuation. These MPRs focus on safety, structural soundness, and sanitation, and an appraiser working a VA file may flag repairs that a conventional appraisal would simply note as condition issues rather than requirements.
Why appraisals come in low or a property becomes ineligible
A handful of recurring issues trip up Virginia transactions, and most are preventable once you know what to look for.
- Thin or outdated comparable sales data, especially in rural areas or during fast-moving markets, can leave an appraiser with limited support for value.
- Deferred maintenance, safety hazards, or failed MPR items on VA files can cap value or stall the loan entirely.
- Eligibility snags, including condo project approval issues, unavailable flood insurance, or zoning and title problems, can derail a file even when the value itself looks fine.
- Simple report errors, like wrong square footage or a miscounted bedroom, happen more often than buyers expect and are worth checking against your own listing details.
A termite inspection finding or an unresolved home inspection item can also show up as a condition concern once the appraiser walks through.
Preparing your home before the appraiser arrives
A little preparation goes a long way toward a smoother visit and a more accurate report.
- Handle curb appeal first: trim landscaping, touch up exterior paint, and fix anything visibly broken.
- Gather permits, receipts for recent improvements, and proof of square footage.
- Clear storage areas, attics, and crawl spaces so every room and utility access point is reachable.
- Make a short list of recent comparable sales in your neighborhood to share if asked.
Cosmetic upgrades like fresh paint or landscaping rarely move the needle much on value, while verified square footage, permitted additions, and resolved safety issues typically do.
Pro Tip: Walk your own home with a flashlight the week before the appointment and check attic access, water heater clearance, and any crawl space entry, since these are common MPR trouble spots on VA files.

A full walkthrough checklist is available in our pre-appraisal preparation guide.
If you disagree with the appraisal: ROV and lender review options
A low appraisal is not always the final word. Here is how to respond.
- Request a borrower-initiated Reconsideration of Value through your lender, which requires you to point out factual errors or suggest up to five alternative comparable sales, per Fannie Mae's ROV guidance. Lenders can accept only one borrower-initiated ROV per appraisal.
- Ask the lender for a desk or field review, or a second appraisal, if the first report seems inconsistent with market conditions.
- File a complaint with the Virginia Real Estate Appraiser Board if you suspect the appraiser violated licensing standards or professional conduct rules.
Verifying a Virginia appraiser's license before you hire one
Virginia's Department of Professional and Occupational Regulation oversees three license classes: licensed residential, certified residential, and certified general, each with its own education and experience thresholds under DPOR's Real Estate Appraiser Board regulations. Appraisal businesses and appraisal management companies operating in Virginia must also register with the board.
- Look up the appraiser's license number directly on the DPOR website before hiring.
- Confirm the appraiser follows USPAP, the uniform standards that govern appraisal practice nationwide.
- Ask about recent experience in your specific neighborhood and request a sample report if you are unsure what to expect.
How a local agent supports your appraisal outcome
Working with an agent who prepares strong comparable data, coordinates scheduling with the appraiser, and flags likely MPR repairs ahead of time tends to smooth out the process. Our team handles these coordination steps for Virginia clients: pulling recent comps, confirming access and documentation ahead of the visit, and advising on repairs that matter for VA files. When a report comes back low, we help clients weigh an ROV against a straight renegotiation.
When ordering your own appraisal makes sense
We generally recommend ordering an independent appraisal for tax appeals, divorce or estate settlements, or high-stakes negotiations where every dollar is contested. Order it early. Waiting until a deal is already stalled narrows your options and adds pressure to the timeline.
— Myra
Get local help before or after your appraisal
We work with Virginia sellers and buyers to prepare for appraisals before they happen and respond effectively when a report comes back lower than expected. Our Home Valuation service gives you a realistic starting number, and our team coordinates documentation, scheduling, and negotiation support around the appraiser's visit. If you are getting ready to list, our Sell My Home page is the place to start.
Reach out whenever you want a second set of eyes on your numbers before a lender's appraiser walks through your door.
FAQ
How much does it cost to get a house appraised in Virginia?
As of May 1, 2026, the standard VA-designated fee for a single-family home appraisal in many Virginia markets is $700, with higher fees for multi-family or manufactured homes. Private, non-VA appraisals often fall in a comparable range depending on property size and location.
What are the new VA appraisal requirements for 2026?
As of May 1, 2026, VA's updated fee schedule sets the standard single-family fee at $700 and maintains a 10-business-day turnaround expectation in many Virginia localities. Appraisers working VA files continue to apply Minimum Property Requirements covering safety, structural soundness, and sanitation.
What will fail a VA appraisal?
VA appraisals apply Minimum Property Requirements focused on safety, structural soundness, and sanitation, so issues like a leaking roof, exposed wiring, or inadequate water supply typically require repair before closing. These standards go beyond what a conventional appraisal would flag.
Do VA appraisers lowball?
VA appraisers follow the same sales-comparison methods used across the industry, and a low value usually reflects thin comparable data or a fast-moving local market rather than bias. If you believe a report contains factual errors, you can pursue a Reconsideration of Value through your lender.
Sources
- VA appraiser fee schedule
- Real Estate Appraiser Board regulations (Virginia DPOR)
- Cost and income approach to value (Fannie Mae)